Best Online Casino Payment Methods for Aussies
 Available in US
See how cards, PayID, bank apps, digital wallets, vouchers and crypto differ across deposits, withdrawals and everyday Australian banking.
Table of Contents
- The Australian Casino Payment Landscape: What Actually Matters
- Phone Payment Casinos: PayID, Bank Apps and the New Cashier
- PayID Casino Payments, Without the Banking Theatre
- Casino Payment Providers: The Companies Behind the Checkout
- How Casino Payment Systems Move Money from Deposit to Cashout
- Instant and Secure Casino Payment Methods for Australian Players
- Fast Casino Payments in Australia: Deposits Are Only Half the Story
- Casino Payment Gateways, Cards and Digital Wallet Rails
- Mobile Casino Payments: Convenience with a Short Memory
- Casino Payment Apps and Vouchers: PayID, Neosurf and Crypto in Practice
The Australian Casino Payment Landscape: What Actually Matters
For Australian players, a casino cashier is less a menu than a small map of jurisdiction, banking infrastructure and practical risk. The best online casino payment methods for Aussies in 2026 are not necessarily the newest or most loudly advertised. They are the routes that fit Australian banking habits, work in the account’s currency, and leave a usable path when a deposit becomes a withdrawal.
The basic choice includes Visa, Mastercard, POLi, cryptocurrency wallets and bank transfers. That range matters because no single method solves every part of the transaction. A card may be familiar at the deposit stage; a bank transfer may become relevant when funds need to leave the casino. A cryptocurrency wallet belongs to a different financial system altogether. The point is not to collect payment buttons like souvenirs. It is to understand what each button can actually do.
Local fit comes before speed
The phrase casino payment methods Australia can suggest a neat local marketplace. The legal picture is less tidy. Australia has no domestically licensed real-money online casino for local players, and no Australian gambling licence exists for casino games because offering that product to Australians is against the law. Under the Interactive Gambling Act 2001, online casino games such as pokies, roulette, blackjack and live dealer tables are prohibited interactive gambling services when offered to an Australian customer.
The Act targets providers rather than individual players. An Australian player is not committing a crime merely by placing a bet at an offshore site. That distinction explains why payment research cannot be separated from operator research. The cashier may accept an Australian card while the business itself operates under an overseas framework.
Only local operators holding relevant licences may offer gambling products to Australian residents, but that principle applies to products that can legally be offered locally. Offshore casino operators commonly rely on licensing authorities such as the Malta Gaming Authority or Curacao. Their licence status should be verifiable through the relevant regulator’s public register. A polished payment page is not proof of anything beyond the existence of a polished payment page.
What a workable cashier should show
A sensible set of online casino payment methods should make several things clear before funds are committed:
- which deposit methods are available to Australian accounts;
- whether the method supports withdrawals as well as deposits;
- whether the cashier accepts Visa, Mastercard, POLi, cryptocurrency wallets or bank transfers;
- which company or processing route handles the payment;
- what identity checks may apply before a first cashout;
- whether the deposit source must match the withdrawal method.
That last point is where many apparently simple arrangements become less simple. A payment method can be excellent for putting money in and unsuitable for taking it out. Vouchers are deposit-only, and a card, wallet or bank route may therefore be needed later. The withdrawal route is not an administrative footnote; it is part of the method’s value from the beginning.
Payment gateways for online casinos often make this distinction look invisible. A row of familiar logos can imply equal access, although the underlying processing conditions may differ. Visa and Mastercard are not interchangeable with POLi, a cryptocurrency wallet or a bank transfer merely because they sit in the same cashier. The visible button is the surface. The route behind it determines what happens next.
The sensible order of checks
The strongest casino payment methods are those that align four questions: Is the operator’s licence verifiable? Is the payment option available to Australian players? Does it suit both the deposit and withdrawal stages? Are the records clear enough to resolve a problem?
That is a more useful standard than calling one option the “best online casino payment method”. It also leaves room for different priorities. Someone seeking an online casino payment by Visa may value familiarity; someone considering Bitcoin may value a crypto wallet’s separation from card banking. Neither preference repairs an unsuitable operator or an unusable cashout route.
The small print remains stubbornly important. Read bonus terms before depositing, retain transaction references, and avoid any site unable to display verifiable licence information. In casino payments, convenience is often the first promise. Compatibility is the part that survives.
PayID Deposit Steps
Choose the casino’s PayID identifier from the available options.
Input the deposit amount and the required reference number in your banking app.
Authorise the payment through your banking environment.
Phone Payment Casinos: PayID, Bank Apps and the New Cashier
A phone payment casino is less about a special casino app than about the banking app already sitting on the phone. For Australian players, the important route is PayID: a bank account connected to a phone number, email address or ABN. The casino supplies its PayID identifier, while the transfer is authorised inside the customer’s own banking environment.
That arrangement changes the character of the cashier. It is no longer a page asking for card details and then sending the transaction through an unfamiliar checkout. The bank app becomes the working counter. The casino provides the destination and the reference; the bank confirms the movement of funds.
How a PayID deposit works on a phone
The process is short, although one small field has disproportionate importance. A PayID deposit requires:
- Selecting the casino’s PayID identifier.
- Entering the deposit amount in the banking app.
- Adding the casino’s reference number.
- Confirming the payment through the bank.
The reference is not decorative paperwork. It helps the casino associate the incoming transfer with the correct account. If it is omitted or entered incorrectly, the payment may require manual attention rather than appearing neatly in the balance.
PayID transfers are available 24 hours a day, seven days a week, including public holidays. PayID casino deposits typically appear within 60 seconds. That timing is what makes the method feel different from a conventional bank transfer: the banking system remains involved, but the cashier does not necessarily become a waiting room.
There is also a quieter privacy advantage. PayID operates within the bank’s own systems without a third party accessing banking credentials. The banking login stays with the bank, rather than being handed to a separate payment page. Security is not the same thing as anonymity, and the casino may still require identity documents before a first cashout. The distinction matters.
The phone number is the address
The familiar logic of banking is built around account numbers. PayID replaces that internal-looking destination with an identifier that can be a phone number, email address or ABN. For a mobile user, the phone number is the most intuitive version: it is already attached to a device, a person and a banking relationship.
That convenience can also make errors feel deceptively unlikely. A transfer can look as simple as sending money to a contact, but the casino’s identifier still needs to be selected correctly. The banking app may display the PayID name before confirmation; that is the moment to check that the intended recipient is shown. A familiar screen does not make an incorrect destination correct.
This is where a phone-based casino payment differs from a generic collection of online casino payment options. Cards, e-wallets and other casino payment solutions each have their own account structures. PayID borrows the ordinary habits of Australian banking and places them inside the casino cashier. The newness is mostly institutional. The buttons are not.
From deposit to withdrawal
The mobile banking route is not limited to putting money into an account. PayID casino withdrawals typically arrive in a bank account within minutes. The casino still has to approve the withdrawal, and that internal step remains separate from the bank transfer itself. A fast banking rail cannot turn an unapproved request into a completed cashout.
This is why the phrase “instant deposit” should not be treated as a complete description of a phone payment casino. The deposit may appear within 60 seconds, while the withdrawal depends first on the operator’s checks and then on the payment route. The cashier has two directions, and they are not mirror images.
A PayID withdrawal also returns funds to a bank account rather than to the phone number as a separate wallet. The phone number is the identifier; the bank account remains the financial destination. That is a small distinction, but it prevents the usual confusion between a payment method and a mobile device.
Banking App Role PayID allows you to use your existing banking app as the transaction counter, keeping your credentials secure within your bank’s system.
What the mobile cashier reveals
The rise of phone-based casino payments says something about the Australian preference for familiar financial infrastructure. A banking app is trusted because it belongs to an existing institution, not because the casino has designed a particularly persuasive checkout. The casino becomes a requester of payment; the bank retains the act of authorisation.
For that reason, the most useful Australian casino payment options are not necessarily the ones with the most elaborate logos. A phone payment casino works when the identifier is clear, the reference is recorded correctly and the transaction can be matched to the account. Glamour is unnecessary. Correct routing is enough.
The practical rule is plain: preserve the payment reference and confirm the PayID destination before authorising the transfer. On a small screen, one missed field can outweigh all the promised speed.
Small screen. Serious paperwork.
PayID Casino Payments, Without the Banking Theatre
PayID is less a separate financial world than a label attached to the banking system already in use. It links a bank account to a phone number, email address or ABN, allowing a casino payment to be directed through the player’s banking app rather than through a card form or wallet balance. The arrangement is distinctly Australian: familiar infrastructure, a short identifier, and no need to hand banking credentials to an outside processor.
PayID transfers run 24 hours a day, seven days a week, including public holidays. When the transfer uses Osko, settlement occurs in seconds. POLi belongs to a different part of the same payment conversation: its payments can take up to a business day. The distinction matters because a casino cashier may present both as near-identical buttons while the underlying route behaves differently.
The PayID deposit sequence
A PayID deposit is operationally plain:
- Select the casino’s PayID identifier.
- Enter the deposit amount and the required reference number in the banking app.
- Confirm the payment.
- Wait for the casino account to recognise the transfer.
PayID casino deposits typically appear within 60 seconds. That speed depends on the payment being addressed correctly. The reference number is not decorative paperwork; it helps the operator match the incoming transfer to the right account. Omitting it or entering it incorrectly can cause significant delays. A casino payment can therefore be technically settled while the player’s balance remains unresolved. Money has arrived. The theatre merely continues backstage.
PayID operates inside the bank’s own systems, without a third party accessing banking credentials. That is one reason the method feels less elaborate than an online casino payment routed through a card processor or an e-wallet. It does not remove the casino’s own checks, however. A fast transfer is not the same thing as an instantly approved account.
Fees and the withdrawal side
Most platforms charge zero transaction fees for PayID at Australian casinos. That describes the casino-side charge; it does not turn every possible bank or account condition into a universal promise. The cashier’s terms remain the relevant place to confirm how a particular operator handles the route.
PayID withdrawals typically arrive in a bank account within minutes. The money still passes through the casino’s internal approval process before it leaves. One specialist payment review reports that some operators approve PayID withdrawals in under ten minutes after internal approval. That is a reported operator practice, not a market-wide service standard. The important separation is between approval and settlement: the bank transfer may be quick, while the casino can take longer to release it.
- Verify the PayID identifier before confirming
- Always include the correct transaction reference
- Check if the withdrawal method matches your deposit source
- Omit the reference number during transfer
- Assume instant cashouts for all deposit methods
- Share banking credentials with third-party interfaces
The withdrawal method may also need to match the deposit source. That makes PayID worth checking before registration as a complete payment route rather than assuming that a convenient deposit button guarantees an equally convenient cashout.
Small checks, large consequences
PayID is straightforward until a detail is wrong. The identifier must belong to the intended casino, the amount must be correct, and the reference must travel with the payment. The banking app confirms the transfer, but the casino still has to reconcile it.
For casino payment risk management, those are modest controls with disproportionate value: retain the transaction reference, verify the PayID identifier before confirming, and distinguish a pending casino balance from a failed bank transfer. PayID removes much of the ceremony. It does not remove the need to read the screen.
Casino Payment Providers: The Companies Behind the Checkout
A casino cashier may show a neat row of logos, but the visible button is only the front desk. Behind it sit payment providers, acquiring banks, wallet operators and processing partners, each handling a different part of the transaction. The player selects a method; the infrastructure decides how that choice is authorised, recorded and passed along.
That distinction matters in an AUD casino. “Visa” or “POLi” names the route visible at checkout, not necessarily the company moving the payment from one account to another. A casino payment provider connects the operator’s cashier with the relevant banking or wallet network. It may transmit an authorisation request, return a success or failure message, record the transaction reference and help reconcile the casino’s internal balance with the money received.
The arrangement is less glamorous than the cashier suggests. It is also where many explanations become vague.
What a provider actually does
Casino payment processing usually involves several linked stages:
- The casino presents an available payment method.
- The provider sends the transaction through the appropriate financial network.
- The bank, card scheme or wallet service authorises or declines it.
- The result returns to the casino, which updates the account balance.
- Transaction records are retained for reconciliation and later checks.
The provider is therefore not the same thing as the bank, the casino or the payment method. Visa and Mastercard are payment methods visible to the player, while a processing partner may route the request behind the scenes. POLi has its own payment flow, and a wallet such as PayPal, Skrill or Neteller maintains a separate account relationship with the customer. The cashier compresses these distinctions into icons. Convenient, but intellectually dishonest.
A casino payment portal is the interface where these routes are assembled. It can display cards, bank-linked payments, wallets or cryptocurrency without implying that one company controls them all. Availability depends on the casino’s commercial arrangements, the provider’s coverage and the player’s location. A method may appear for deposits but not for a casino payment withdrawal, because receiving money requires a different processing path and separate operational approval.
Why the provider matters to Australian players
The provider affects more than whether a payment button works. It can determine which currency is supported, what transaction information is passed to the casino and whether a payment can be matched to the correct account. It also forms part of the audit trail when a deposit is disputed or a withdrawal is being reviewed.
Payment Provider A company that connects the casino’s cashier with banking or wallet networks to authorise and record transactions.
PayID illustrates the difference clearly. PayID operates within the bank’s own systems, without a third party accessing banking credentials. A casino may still use a processing partner to present instructions or reconcile the incoming transfer, but the banking authentication remains within the bank’s environment. That is not the same arrangement as entering card details into a third-party checkout.
The legal setting gives this infrastructure an awkward edge. The Interactive Gambling Act 2001 prohibits Australian companies from offering certain forms of interactive gambling to Australian residents. The Act targets operators, not individual Australian players. Payment processing does not turn an offshore casino into a domestically licensed one, nor does a familiar provider create an Australian casino licence where none exists.
Questions worth asking before a deposit
A sensible review of an online casino payment provider should establish:
- Which company processes the deposit?
- Is the method available for both deposits and withdrawals?
- Will the transaction be recorded in AUD or converted elsewhere?
- What reference or transaction details are required?
- Does the casino explain who handles payment support when something fails?
The provider’s name may be absent from the first cashier screen. That is a reason to read the payment terms, not to assume the casino and the financial intermediary are the same business. A polished checkout is presentation. The provider is the machinery underneath.
How Casino Payment Systems Move Money from Deposit to Cashout
A casino payment system is not a single pipe running from a bank account to a game balance. It is a sequence of permissions. Money arrives, the account records where it came from, the operator may request identity documents, and only then does the withdrawal route become meaningful. The cashier is less a door than a small bureaucracy with buttons.
The account lifecycle
An online casino payment system normally separates four stages:
- Deposit selection — the player chooses an available card, bank route, wallet or other method and submits the transaction.
- Balance crediting — the casino records the payment and adds funds according to its internal processing rules.
- Verification — identity and payment ownership checks may be required before winnings can be released.
- Cashout approval — the operator reviews the withdrawal and sends it through an eligible route.
The payment used to fund an account does not automatically determine how quickly money can leave it. Deposits and withdrawals are separate transactions, even when the cashier displays them beside one another. A card can be convenient for adding funds while its withdrawal route takes longer. A bank transfer may be the eventual destination even when the original deposit arrived through another channel.
That distinction matters because most casinos require the withdrawal method to match the deposit source. Where a direct return is unavailable, the cashier may require an alternative route such as a bank transfer, cryptocurrency or an e-wallet. The practical question is therefore not simply whether a method appears under “Deposit”. It is whether the same account can use it for cashout.
Where verification fits
Identity checks are part of the transaction chain, not an optional interruption. Any regulated operator will ask for documents before a first cashout; a claim about withdrawing without identity verification usually means the check has been postponed, not abolished. The operator may also need to establish that the payment method belongs to the account holder.
This is where the legal shape of the Australian market becomes difficult to ignore. The Interactive Gambling Act 2001 prohibits Australian companies from offering certain forms of interactive gambling to Australian residents. It targets operators rather than individual Australian players. That does not turn every offshore cashier into a domestic service, nor does it create an Australian casino licence.
Timing begins after approval
The withdrawal clock is not necessarily running while a request waits for internal review. Once a route is available and the casino has approved the transaction, the expected delivery windows differ:
- Debit and credit card withdrawals: 1–5 business days
- Bank-transfer withdrawals: 3–7 business days
A payment system therefore has two calendars: the operator’s approval process and the external rail’s settlement time. Treating a deposit as proof of a fast cashout is the oldest trick in the cashier’s modest theatre. Deposits are designed to enter. Withdrawals must be authorised to leave.
Instant and Secure Casino Payment Methods for Australian Players
Choosing a suitable payment method can make casino deposits and withdrawals more convenient for Australian players. This list highlights operators with clearly stated licensing, bonus, minimum-deposit or payout details relevant to payment-focused research.
License: Curacao eGaming Licence · Min. deposit: A$10 Aussie Play is listed with a Curacao eGaming Licence and a minimum deposit of A$10. These details make it a straightforward option to review for players focused on entry-level deposit requirements.
License: Curacao eGaming Licence · Min. deposit: A$10 WinSpirit operates under a Curacao eGaming Licence and lists a minimum deposit of A$10. It is notable for its clearly stated licensing and accessible minimum deposit.
License: Curacao eGaming OGL/2023/174/0082 (Dama N.V.) · Bonus: up to A$10,000 + 500 free spins across 4 deposits · Min. deposit: A$15 LevelUp Casino holds Curacao OGL/2023/174/0082 through Dama N.V. Its offer includes up to A$10,000 and 500 free spins across four deposits, with a minimum deposit of A$15.
License: Curacao Gaming Control Board (TechSolutions Group N.V.) · Bonus: 100% up to A$250 + 100 free spins (1st deposit) Bizzo Casino is licensed by the Curacao Gaming Control Board through TechSolutions Group N.V. It features a first-deposit bonus of 100% up to A$250 plus 100 free spins.
License: Curacao · Bonus: up to A$10,000 multi-stage + 500 free spins · Min. deposit: A$20 (POLi) Lucky Dreams is listed with a Curacao licence and offers a multi-stage bonus of up to A$10,000 plus 500 free spins. Its stated minimum deposit is A$20 when using POLi.
License: Curacao OGL/2024/1335/0780 · Bonus: up to A$1,000 + 150 free spins, wager-free · Min. deposit: EUR 20 Vegaz Casino holds Curacao OGL/2024/1335/0780. It offers up to A$1,000 plus 150 free spins with no wagering requirement, and lists a minimum deposit of EUR 20.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) · Bonus: 100% up to A$10,000 + 100 free spins GoldenCrown is licensed by the Curacao Gaming Control Board under OGL/2023/176/0095 through Hollycorn N.V. Its stated promotion is 100% up to A$10,000 plus 100 free spins.
License: Curacao Gaming Control Board · Bonus: up to A$5,000 + 400 free spins JustCasino is listed with a Curacao Gaming Control Board licence. Its main stated offer is a bonus of up to A$5,000 plus 400 free spins.
License: Curacao · Bonus: 100% up to A$500 + 200 free spins, 10x wagering · Payout speed: crypto 30-60 minutes, fiat 1-5 days · Min. deposit: A$10 Wild Tokyo is listed with a Curacao licence and offers a 100% bonus up to A$500 plus 200 free spins, with 10x wagering. It also states crypto payout times of 30–60 minutes and fiat payout times of 1–5 days, alongside a minimum deposit of A$10.
License: Curacao, operated by Dama N.V. · Bonus: 325% up to 5.25 BTC + 250 free spins across 4 deposits 7Bit Casino is licensed in Curacao and operated by Dama N.V. Its promotion is 325% up to 5.25 BTC plus 250 free spins across four deposits.
Speed is easy to advertise and harder to define. A card deposit may appear instantly in the casino balance while the same route is less useful when money needs to come back out. Security has a similar complication: a familiar logo is not, by itself, proof of a sound transaction. The sensible comparison is therefore between the payment method, the casino’s handling of it, and the point at which funds become available.
Cards: familiar, quick deposits
Visa and Mastercard remain popular online casino payment methods because they are widely recognised and deposits are typically instant at Australian-friendly casinos. That makes them practical for funding an account without waiting for a bank process to complete.
The important distinction is between recognition and protection. A card is a secure casino payment method only within a checkout that handles the transaction properly and belongs to an operator with verifiable licensing information. The card brand supplies the rail; it does not turn an unlawful or opaque casino into a safe one.
Visa/Mastercard Instant deposits
POLi Fast bank-integrated transfers
E-wallets Separated account management
Cryptocurrency Fast, irreversible transactions
Cards also illustrate why “instant” should be attached to the deposit, not to the whole payment relationship. The arrival of funds in the casino balance says little about the later withdrawal process. A fast front door can still lead to a slower exit.
POLi: bank access without a separate wallet
POLi deposits are almost instant and widely accepted at Australian online casinos. Its appeal lies in using the existing bank environment rather than asking players to maintain another payment account. For a casino payment integration, that familiar route can make the cashier feel less like a financial detour.
Yet convenience does not remove the need for checking. The casino must list POLi explicitly, and the transaction should be completed through the expected banking flow. A method can be popular without being suitable at every operator. Availability is part of security because a payment option that appears in an advertisement but not in the actual cashier is not a usable option.
E-wallets: separation as a safety feature
Skrill and Neteller occupy a different position. They create a layer between the casino and the player’s main bank account, which can make account management more orderly. Their withdrawals typically process within hours at Australian casinos, though that stated processing time still belongs to the casino’s handling of the request, not to a universal promise.
This separation can be valuable, but it introduces another account to protect and verify. A secure casino payment method is never secure in isolation: the wallet account, casino account and identity checks all form part of the same chain.
Cryptocurrency: speed with irreversible edges
Cryptocurrency deposits and withdrawals can be instant at Australian casinos and have no currency conversion fees. That combination makes crypto attractive where speed and currency handling matter.
It is also the least forgiving route when transaction details are wrong. A mistyped wallet address is irreversible, and sending Tether as an ERC-20 token to a TRC-20 address may be unrecoverable. Instant payment casino marketing tends to celebrate the first adjective and quietly omit the second. Speed is useful only when the destination and network are correct.
Irreversible Risk Cryptocurrency transactions are irreversible; a mistyped wallet address or incorrect network choice will result in a permanent loss of funds.
The strongest comparison is therefore not “fast versus slow”. It is quick access versus controlled recovery. Cards, POLi, e-wallets and cryptocurrency can all be practical, but the safer choice is the one whose deposit behaviour, withdrawal access and verification requirements are understood before money is sent.
Fast Casino Payments in Australia: Deposits Are Only Half the Story
An instant deposit creates a pleasing illusion: the casino balance changes, the cashier closes, and the money appears to have crossed the whole distance. It has not. Depositing is an authorisation event; withdrawing is a release of funds, often subject to the casino’s processing queue and the receiving method’s timetable. The difference matters more than the word fast placed beside a payment button.
For Australian players comparing casino payment methods, the useful question is therefore not simply how quickly money enters an account. It is how long the selected route takes after a withdrawal has been requested and approved.
Withdrawal times by method
| Withdrawal method | Expected processing time |
|---|---|
| Cryptocurrency | Under one hour |
| Skrill or Neteller | 2–24 hours |
| Debit or credit card | 1–5 business days |
| Bank transfer | 3–7 business days |
Cryptocurrency has the shortest stated window in this comparison: expected withdrawals take under one hour at Australian casinos. That speed is tied to the digital-asset route rather than to the casino cashier alone. The receiving wallet must still be identified correctly, because a mistyped wallet address is irreversible. Fast does not mean forgiving.
E-wallets such as Skrill and Neteller occupy the next position, with expected withdrawals taking 2–24 hours. Their appeal is less theatrical than an instant balance update but more useful: the funds are directed to a separate digital account rather than sent back through a card network. For an Australian casino payment arrangement, that can make the withdrawal route clearer from the outset.
Cards are slower. Debit and credit card withdrawals are expected to take 1–5 business days. The deposit may have been processed almost instantly, yet the return journey follows a different timetable. This is the small administrative joke hidden inside many “fast payment casino” claims: the front door opens quickly; the back door keeps office hours.
Bank transfers take longer still, with an expected window of 3–7 business days. They are not the elegant option when speed is the only measure, but timing is only one part of a payment decision. A casino payment Australia page that highlights rapid deposits while leaving withdrawal windows in fine print is describing half a transaction.
Trustly, STICPAY and Mastercard may appear in discussions of online casino payment options, but a named button does not establish a withdrawal time. The published windows above are the usable benchmark for Australian casino payment methods: cryptocurrency, e-wallets, cards and bank transfers. The cashier’s promise begins where the deposit ends.
Casino Payment Gateways, Cards and Digital Wallet Rails
A casino payment gateway is the visible counter between an account and the financial system behind it. The cashier may show neat buttons for Visa, Mastercard, Skrill or Neteller, yet those buttons do not necessarily represent separate routes from end to end. They can lead into different authorisation flows, currencies, verification checks and settlement arrangements.
That distinction matters because a familiar logo is not a promise about the whole transaction. Visa may be displayed as a deposit option while withdrawals follow another route. Skrill may appear beside a card icon, but its cashout process is governed by the wallet rather than the card network. The checkout is the stage; the rails are underneath.
Essential Payment Advice
- Always verify the withdrawal method before making a deposit
- Use transaction references to avoid manual reconciliation delays
- Distinguish between deposit speed and withdrawal approval time
What the gateway actually does
At the payment screen, the gateway passes the selected method to the relevant processing system, requests authorisation and returns the result to the casino cashier. For a card deposit, this generally means entering card details and allowing Visa or Mastercard to approve the payment. Deposits made with either card are typically instant at Australian-friendly casinos.
A wallet-based payment has a different shape. The cashier sends the transaction to Skrill or Neteller, where the wallet account authorises it. The casino then receives confirmation without the wallet becoming interchangeable with a card. Withdrawals through Skrill and Neteller typically process within hours at Australian casinos, which is why the same button can have a very different role when money is leaving rather than entering the account.
The wording on the cashier can obscure this. “Card”, “wallet” and “banking” describe the front end; they do not fully explain who authorises the payment, where credentials are entered or which route handles a withdrawal.
The limits of a polished checkout
Payment technology is often presented as if it were a single smooth machine. It is more like a railway station with excellent signage: the destination may be clear, while the track changes after the platform.
A gateway may also list digital-wallet brands that are not confirmed for every Australian account or every transaction direction. Apple Pay, Google Pay and Klarna should therefore be treated as possible interface labels, not assumed casino payment methods. Availability must be shown in the cashier itself, and the chosen option must support the required transaction route.
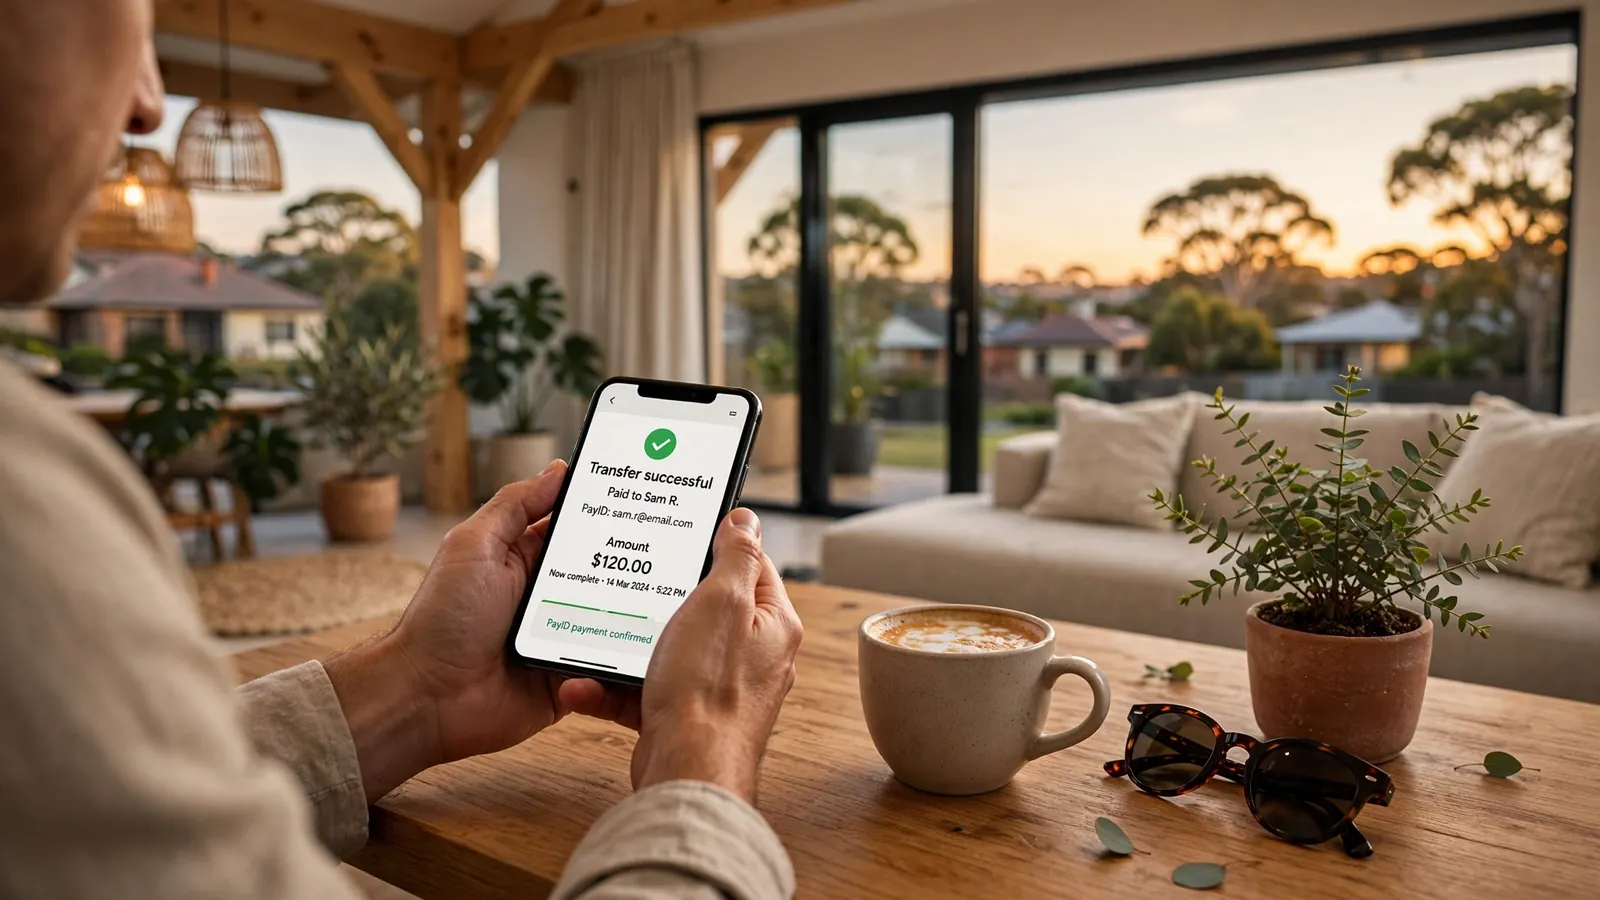
PayID illustrates the difference between a payment button and an intrusive intermediary. It operates within the bank’s own systems, without a third party accessing banking credentials. The gateway can direct the payment, but the banking authorisation remains with the bank.
Before depositing, the material checks are plain: confirm the displayed method, the authorisation screen and whether withdrawals use the same rail. A familiar logo is only the beginning. The small print is the actual infrastructure.
Mobile Casino Payments: Convenience with a Short Memory
A mobile casino payment is less a separate financial product than a way of reaching the cashier. The same card, wallet or bank-based option may appear on a phone, yet the small screen changes how the transaction is handled. Banking apps open over the casino browser, confirmation screens disappear into notifications, and a reference number can be copied once and then vanish into the digital undergrowth.
That is why mobile convenience needs a short memory of its own.
Banking apps and mobile casino payments
PayID is the clearest Australian example of a casino payment completed on a phone without handing banking credentials to a third party. The transfer runs through the bank’s own systems. PayID is available around the clock, including public holidays, and PayID casino deposits typically appear within 60 seconds.
The mobile sequence is precise:
- Select the casino’s PayID identifier.
- Enter the deposit amount in the banking app.
- Add the casino’s reference number.
- Confirm the payment.
The reference number is not decorative paperwork. It connects the bank transfer with the casino account. Omitting it, or entering it incorrectly, can cause significant delays. A screenshot of the completed payment is therefore worth keeping, alongside the reference number and transaction record. Mobile interfaces are designed for flow, not archives.
PayID through Osko settles in seconds. POLi, although also usable from a mobile banking flow, can take up to a business day. The distinction matters when a cashier presents both options with similarly polished buttons. A casino with mobile payment access is not necessarily offering identical settlement behind every button.
Browser, app and notification habits
Some players use a casino’s mobile-optimised website; others move between a banking app, an email confirmation and the casino cashier. Either route can work, but the evidence trail is easier to lose on a phone than on a desktop. A closed tab can remove the visible transaction context. A banking notification may show that money left the account without showing which casino reference was attached.
Are mobile payments secure?
Yes, using PayID through a banking app keeps your credentials within your bank’s secure environment.
Why is my deposit not showing?
It is often due to an incorrect or missing transaction reference number required by the operator.
This is particularly awkward when support needs to trace a missing deposit. The useful record is not merely “payment made”, but the amount, time, destination identifier and reference number. Mobile payment systems reward speed and punish forgetfulness. A very modern arrangement.
Wallet-based options follow the same principle: the phone is the access environment, not proof that the underlying method is mobile-specific. A digital wallet opened in a browser remains subject to its own account checks and the casino’s cashier rules. The same applies to card payments entered on a handset. A smaller screen changes the choreography, not the transaction’s obligations.
For Australian players, the sensible test is therefore practical rather than fashionable: whether the method is clearly displayed in the cashier, whether the mobile banking record can be retained, and whether the payment reference remains available if the deposit does not appear. Convenience lasts seconds. Records last longer.
Casino Payment Apps and Vouchers: PayID, Neosurf and Crypto in Practice
A casino payment app is rarely just a button in a cashier. It is a small administrative system: a banking app may approve a PayID transfer, while a crypto wallet requires the correct address and network. A prepaid instrument follows a different logic again. Money is loaded first, then spent through a code.
That distinction matters because the payment method selected for a deposit may not be available for a withdrawal. Vouchers are generally deposit-only, so a separate cashout route has to be planned from the beginning. A wallet address entered incorrectly is irreversible, an unusually severe consequence for a box that often looks no more complicated than a shopping checkout.
Neosurf prepaid vouchers
Neosurf is the clearest example of a prepaid casino payment. Its denominations run from AUD 10 to AUD 250, and each voucher uses a unique 10-digit PIN. The PIN is entered in the casino cashier, rather than exposing bank-card details or banking credentials to the operator.
The voucher remains valid for up to 18 months. That gives the instrument a useful quality in a market where payment records can become scattered across banking apps, emails and casino account pages: the value is represented by one code. It also creates a simple obligation. The code must be stored securely.
The deposit amount must be equal to or less than the voucher’s remaining balance. A single voucher cannot exceed its stated denomination, but multiple Neosurf prepaid vouchers can be used across separate transactions when a larger total deposit is required. The deposit should appear in the casino account within seconds of entering the voucher code.
Before using it, the cashier needs to list Neosurf explicitly as a qualifying deposit method. That check is more important than the logo. A voucher cannot be turned into a withdrawal method merely because it was accepted for funding.
PayID, crypto and the separate cashout
PayID belongs to the app-linked side of the payment landscape. It connects a bank account with a phone number, email address or ABN, while the transaction itself is confirmed inside the bank’s own app. Crypto sits further away from conventional banking: the wallet is the account, and the address is the instruction.
Neither arrangement removes the need to verify the withdrawal route. A voucher-funded account may require a bank transfer, cryptocurrency or an e-wallet for cashout, while crypto demands careful checking of the wallet network. Tether sent as an ERC-20 token to a TRC-20 address may be unrecoverable.
The practical rule is plain: confirm that the chosen method supports both deposits and withdrawals before registering, then keep the transaction reference and payment details. Convenience is useful. Memory is not.
Is Neosurf a safe payment method for online casino deposits?
Neosurf can limit the exposure of your banking details because deposits use a unique 10-digit PIN. However, it is deposit-only, vouchers may incur a retail service fee of around 3%–5%, and the casino’s licence should still be verified.
What payment methods do top Australian online casinos accept?
Australian players need access to Visa, Mastercard, POLi, cryptocurrency wallets and bank transfers. Some casinos also support PayID, while Skrill and Neteller are commonly used for withdrawals.
How do operators verify user identity?
Operators may require identity checks before a first withdrawal and may check that the deposit source matches the withdrawal method. Players should retain transaction references and review the casino’s verification requirements before depositing.
Are there state versus international licensing differences?
Australia has no domestic licence for real-money online casino games offered to local players. Offshore casinos may operate under licences such as those issued by the Malta Gaming Authority or Curacao, which should be checked in the regulator’s public register.
Written by the editors at Betting Top 10 Australia.